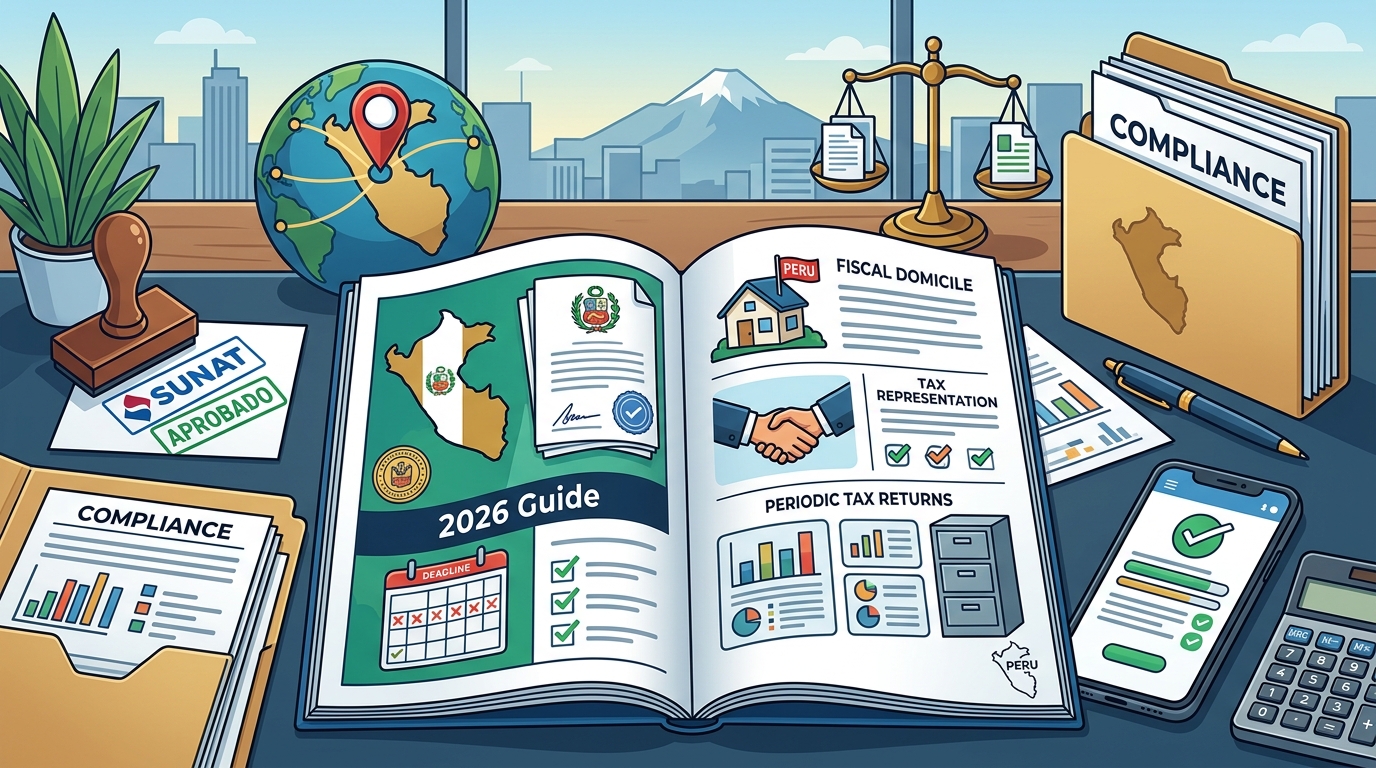
Foreign-owned companies in Peru must maintain a registered fiscal domicile, a tax representative, and file periodic tax returns to remain active. This guide details the specific obligations for IGV, income tax, and corporate governance. It explains how to stay compliant with SUNAT and corporate law without relocating to Lima.
IGV Obligations
Impuesto General a las Ventas (IGV) is a value-added tax applied to the sale of goods and services in Peru. It is the primary consumption tax in the country. Most businesses operate under a standard rate of 18%. This tax is collected from customers and remitted to the state.
Registration and Filing
Companies must register with SUNAT to collect IGV. Registration is mandatory if annual sales exceed the threshold for small taxpayers. Once registered, the company must file monthly IGV returns. The return reports sales, purchases, and the net tax payable. Failure to file on time results in fines and interest.
Invoice Requirements
Issuing valid electronic invoices is a core compliance duty. Invoices must include the RUC of both parties and the IGV amount. The format must comply with SUNAT's electronic standards. Keeping digital records is essential for audits. Setting up a company in Peru includes obtaining the RUC required for this process.
Income Tax Filing
Corporate income tax is a levy on the net profit of a company. In Peru, the standard rate is 29.5%. This tax is calculated on the difference between total income and deductible expenses. Companies must file an annual return and make monthly provisional payments.
Provisional Payments
Monthly provisional payments are due by the 12th of the following month. These payments are based on the previous year's profit or a fixed percentage of sales. The final annual return is filed by April 30. Any difference between provisional payments and the final tax is settled at that time.
Withholding Taxes
Annual Shareholder Meetings
An annual shareholder meeting is a mandatory corporate governance event. It is required for all corporations, including the S.A.C. structure. The meeting must occur within the first three months of the fiscal year. Its primary purpose is to approve the annual financial statements.
Quorum and Minutes
Meetings require a quorum to be valid. The quorum is typically 50% of the shares plus one. Decisions are made by majority vote. Minutes of the meeting must be recorded in the corporate books. These books must be legalized by a notary. Failure to hold the meeting can lead to legal complications and fines.
Director Appointments
Shareholders appoint directors during the annual meeting. Directors serve for a fixed term. Their powers are defined in the bylaws. For foreign-owned companies, the legal representative acts on behalf of the company. Periodical services can help manage these ongoing corporate duties.
Comparison of Key Obligations
| Obligation | Frequency | Authority | Key Document |
|---|---|---|---|
| IGV Return | Monthly | SUNAT | Electronic Invoice |
| Income Tax Provisional | Monthly | SUNAT | Provisional Payment Form |
| Income Tax Annual | Annual | SUNAT | Annual Tax Return |
| Shareholder Meeting | Annual | Corporate Law | Legalized Minutes |
Key Takeaways
- IGV is a monthly obligation requiring electronic invoicing and remittance to SUNAT.
- Corporate income tax requires monthly provisional payments and an annual return by April 30.
- Withholding taxes on third-party payments are a critical compliance area often missed.
- Annual shareholder meetings must be held within the first quarter of the fiscal year.
- Corporate books, including minutes, must be legalized by a notary annually.
- A registered fiscal domicile and tax representative are mandatory for foreign-owned companies.
- Non-compliance leads to fines, interest, and potential deregistration.
- Remote management is possible with the right legal infrastructure in place.
Frequently Asked Questions
Can a foreign company operate in Peru without a local representative?
No. Peruvian law requires a tax representative resident in Peru. This person signs tax documents and acts before SUNAT. Without this, the company cannot remain in good standing.
What is the deadline for the annual income tax return?
The annual return is due by April 30. This applies to the fiscal year ending December 31. Late filing incurs penalties and interest.
Do I need to be in Peru to hold the shareholder meeting?
No. The meeting can be held remotely or through a representative. However, the minutes must be formalized and legalized in Peru. A local legal representative can facilitate this process.
What happens if I miss an IGV filing?
SUNAT imposes fines for late filing. Interest accrues on any unpaid tax. Repeated non-compliance can lead to the suspension of the company's tax status.
Is the S.A.C. structure suitable for foreign investors?
Yes. The S.A.C. is designed for closely held companies. It allows 100% foreign ownership. It does not require a board of directors, simplifying governance.
How do I maintain my fiscal domicile?
Can I manage the company entirely from abroad?
Yes. With a legal representative and fiscal domicile, you can manage operations remotely. The representative handles local legal and tax interactions on your behalf.
What are the penalties for non-compliance?
Conclusion
Compliance in Peru is manageable with the right structure. You need a fiscal domicile, a tax representative, and a system for filing taxes. Peru Legal Setup provides the legal infrastructure to keep your company active and compliant from abroad. We handle the local requirements so you can focus on your business. Book a consultation to discuss your specific needs.